Microeconomics is a branch of economics that analyzes the economic decisions of individuals and businesses, focusing on exploring the fundamental elements of economic activity and their effects. It helps us understand how consumer and producer behavior interacts in markets and the economic outcomes that result.
This material covers the key elements of microeconomics and explores in depth the economic decision-making processes of individuals and businesses, the laws of demand and supply, and market structure and competition.
The Concept of Microeconomics
 Understanding Microeconomics
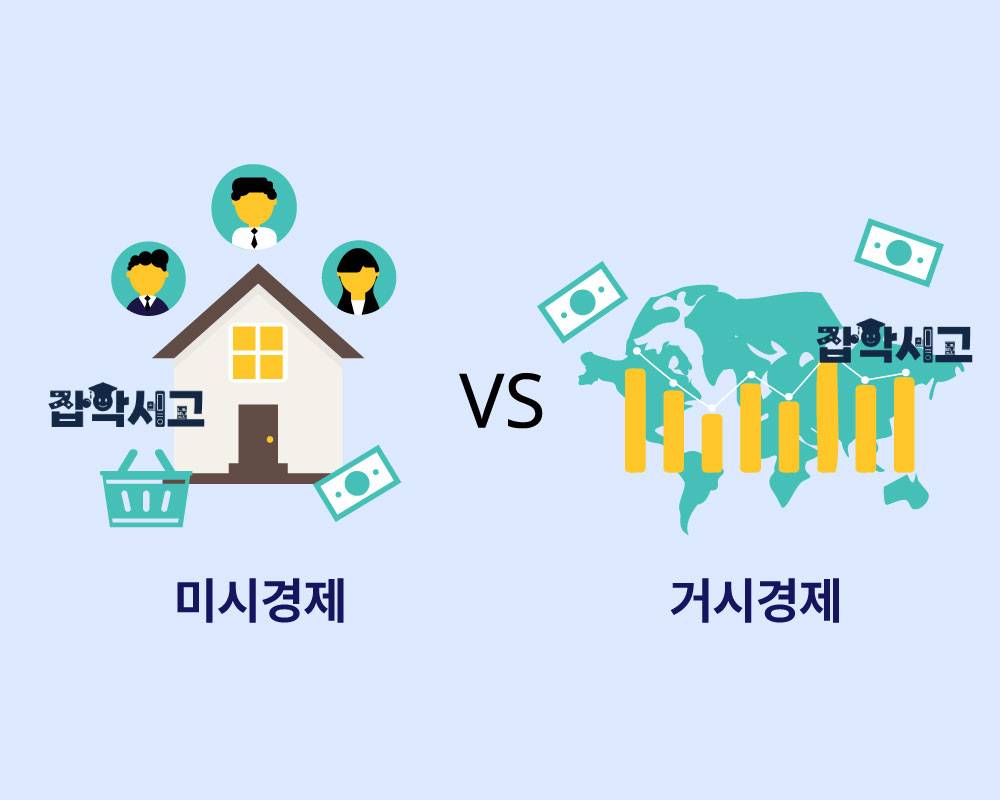
Microeconomics is a branch of economics that focuses on analyzing the decision-making processes of individual economic agents. Here, economic agents refer to individuals, households, businesses, and others, and the field examines how they use and allocate limited resources among various options. Microeconomics provides an analysis of how these agents make decisions and what outcomes those decisions produce within markets.
The core of microeconomics includes demand and supply, price determination, market structure, consumer behavior, and businesses' production decisions. These concepts explain how individual economic agents interact and provide a foundation for understanding how their behavior affects the overall economy.
Unlike macroeconomics, microeconomics focuses on analyzing individual markets, specific industries, or markets for particular goods rather than the economy as a whole. In this process, microeconomics discusses efficient resource allocation, market failure, and the need for government intervention, exploring how economic agents' choices are connected to social welfare.
Ultimately, the concept of microeconomics involves understanding and analyzing economic activity from a microeconomic perspective, thereby supporting better economic decisions and helping improve the economic efficiency of individuals, businesses, and society as a whole.
Reference Material
 What Is Macroeconomics?
Microeconomics: Analyzing Individuals' Economic Decision-Making Processes
 What Is Microeconomics?
Individuals' Consumption Decisions and Evaluation Processes
Individuals' economic decision-making processes are essential activities for survival and prosperity, shaped by a combination of numerous factors. First, each individual evaluates various consumption options based on their income and limited resources. Prices, personal preferences, and needs are considered in this process.
The Role of Marginal Utility and Consumer Decision-Making
Second, consumers make decisions based on marginal utility. Marginal utility refers to the satisfaction provided by additional consumption, and consumers adjust their choices to maximize it. For example, the more often the same good is consumed, the more the satisfaction it provides tends to decline.
The Importance of Budget Constraints and Opportunity Cost
Third, budget constraints have an important influence on consumers' choices. Consumers explore various approaches to find the optimal combination of consumption within their limited income. The concept of opportunity cost is very important in this process. This is because making a particular choice requires giving up the opportunity to make another choice.
Market Prices and the Law of Demand
Fourth, market prices have a major influence on consumers' choices. When the price of a good rises, demand for it tends to decrease, while demand tends to increase when its price falls. This is called the law of demand. Consumers respond sensitively to price changes to optimize their budgets.
Uncertainty and Risk Management Strategies
Fifth, uncertainty and risk factors also have a major influence on individuals' economic decisions. In uncertain situations, consumers try to manage risk through various strategies, such as holding reserve funds or purchasing insurance. They do so to secure economic stability.
Time Value and the Timing of Consumption
Finally, individuals consider time value when making consumption decisions. In other words, they compare the satisfaction from current consumption with the satisfaction from future consumption to determine the appropriate timing of consumption. This is related to the concept of the discount rate, and individuals prefer current consumption when it provides greater satisfaction than future consumption.
Understanding Decision-Making Processes in Microeconomics
The factors discussed above play important roles in individuals' economic decision-making processes. As all these factors interact, consumers strive to achieve their goals as fully as possible. This understanding enables better economic choices and contributes to greater efficiency in economic activity.
Businesses' Economic Choices and Their Impact
 How Do Businesses Affect the Economy?
Optimal Allocation of Factors of Production and Cost Reduction
Businesses make economic choices to maximize efficiency in production and operations. First, businesses seek to reduce costs and maximize revenue through the optimal allocation of factors of production. To do so, they efficiently combine human resources, material resources, capital, and other inputs.
Forecasting Market Demand and Adjusting Output
Second, businesses forecast market demand and adjust their output. This is directly linked to inventory management, and businesses closely analyze market trends to avoid overproduction or underproduction. Overproduction increases inventory costs, while underproduction can result in missed sales opportunities.
The Importance of Technological Innovation and Research and Development
Third, businesses strengthen their competitiveness through technological innovation and research and development (R&D). Technological innovation plays an important role in increasing productivity, creating new market opportunities, and reducing costs. To achieve this, businesses continuously invest in R&D and develop new products and services.
Pricing Strategies and Securing a Market Position
Fourth, businesses use pricing strategies to secure their position in the market. Through various pricing strategies, they analyze consumers' price sensitivity and set optimal prices. This serves as an important factor in ensuring profitability.
Social Responsibility (CSR) and Corporate Image
Fifth, businesses' economic choices also take social responsibility (CSR) into account. Businesses build a positive brand image and promote long-term operational stability through environmental protection, contributions to society, ethical management, and other activities. This is also directly linked to business sustainability.
Entering Global Markets and Seeking Growth Opportunities
Finally, businesses seek growth opportunities by entering global markets. Globalization requires strategies for opening up new markets, expanding the range of products and services, and responding to diverse economic environments. Through these efforts, businesses strengthen their international competitiveness and expand their presence in global markets.
The Long-Term Effects of Businesses' Economic Choices
Businesses' economic choices are closely connected not only to short-term performance but also to long-term sustainability. These choices strengthen businesses' competitiveness, enable them to respond flexibly to the economic environment, and ultimately play an important role in ensuring their long-term survival and growth.
The Foundations of Microeconomics: The Laws of Demand and Supply
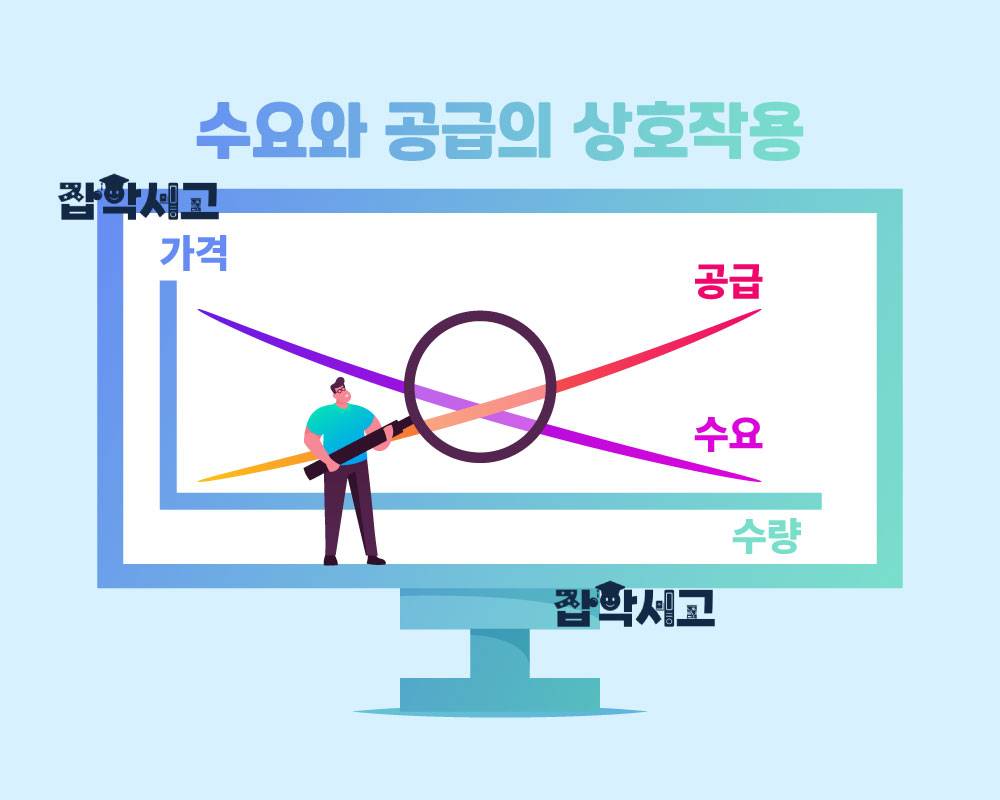 The Interaction of Demand and Supply
The Law of Demand: The Relationship Between Price and Quantity Demanded
One of the core concepts of microeconomics is the laws of demand and supply. First, according to the law of demand, when all other conditions remain constant, a rise in the price of a good reduces the quantity demanded, while a fall in its price increases the quantity demanded. This is a fundamental principle that explains consumers' purchasing behavior.
The Law of Supply: The Relationship Between Price and Quantity Supplied
Second, the law of supply explains the relationship between price and quantity supplied. When prices rise, suppliers tend to supply more goods, while they tend to reduce the quantity supplied when prices fall. This is a strategy for producers to maximize profits.
Determining Market Prices: The Interaction of Demand and Supply
Third, the interaction of demand and supply is an important factor in determining market prices. A market price forms at the point where demand and supply are in balance, and this is called the equilibrium price. The equilibrium price plays an important role in the efficient functioning of a market.
Changes in Market Equilibrium: Shifts in Demand and Supply
Fourth, changes in demand and supply can alter market equilibrium. For example, when the introduction of new technology reduces production costs, supply increases, which can lower the equilibrium price. Conversely, when consumers' preferences shift toward a particular good, demand for that good increases, and the equilibrium price may rise.
External Market Factors: Their Effects on Demand and Supply
Fifth, factors outside the market can affect demand and supply. For example, government regulation, policy changes, and natural disasters can change market conditions and shift demand and supply curves. These factors increase uncertainty in the market.
The Elasticity of Demand and Supply: Responses to Price Changes
Finally, the elasticity of demand and supply is an important indicator that measures responses to price changes. The price elasticity of demand indicates changes in quantity demanded resulting from price changes, while the price elasticity of supply explains changes in quantity supplied. Higher elasticity indicates greater sensitivity to price changes, and this information plays an important role in developing business strategies.
The Importance of the Laws of Demand and Supply
The laws of demand and supply are essential to understanding the basic principles of microeconomics. Based on these laws, market prices and equilibrium can be analyzed, and economic decisions can be made by considering external factors and elasticity. This understanding improves the efficiency of economic activity and contributes to the development of successful market strategies.
Market Structure and Competition: Businesses' Strategic Responses
 How Can Businesses Respond Strategically to Different Market Structures?
Perfectly Competitive Markets: The Role of Price Takers
Market structure has a major influence on businesses' competitive strategies. First, in perfectly competitive markets, numerous businesses offer identical products, and entry into and exit from the market are unrestricted. In this case, individual businesses have almost no pricing power and act as price takers that accept the market price. Therefore, businesses' main strategy is to focus on reducing costs and maximizing efficiency.
Monopoly Markets: Pricing Power and Market Dominance
Second, in a monopoly market, a single business dominates the market and has pricing power. A monopolist can raise barriers to market entry, maintain high prices, and suppress competition. This can cause problems related to limited consumer choice, and the business seeks to use this situation to maximize profits.
Oligopoly Markets: Competition and Cooperation Among a Few Businesses
Third, in an oligopoly market, a small number of businesses dominate the market, and competition and cooperation among them play important roles. Oligopolists tend to control the market by adjusting prices and output and sometimes seek to maximize profits through collusion. Such anticompetitive conduct may attract the attention of regulatory authorities, and managing conflicts and cooperating among businesses become key strategies.
Monopolistically Competitive Markets: Product Differentiation and Pricing Power
Fourth, in monopolistically competitive markets, numerous businesses offer similar but differentiated products, and each business has some pricing power. Businesses secure a competitive advantage through product differentiation, emphasizing brand image, quality, service, and other attributes. This provides consumers with a variety of choices, and businesses focus on innovation and marketing strategies.
Businesses' Strategic Responses: Developing Strategies According to Market Structure
Fifth, businesses' strategic responses vary depending on market structure and competitive conditions. In perfectly competitive markets, reducing costs and improving efficiency may be the main strategies, while innovation and maintaining market power are important in monopoly markets. In oligopoly markets, cooperation with competitors and conflict management become key tasks, while product differentiation and customer satisfaction are central to strategy in monopolistically competitive markets.
Changes in Market Structure and Business Flexibility
Finally, changes in market structure have a major influence on businesses' strategic responses. Technological advances, regulatory changes, globalization, and other factors alter market structure, and businesses must develop flexible strategies accordingly. This is an essential process for managing market uncertainty and promoting sustainable growth. Businesses must develop their ability to adapt to changing environments and seek new opportunities.
The Importance of Market Structure and Strategic Responses
For businesses to compete successfully in the market, it is essential to understand market structure accurately and develop appropriate strategies. By varying their strategic responses according to market structure, businesses can achieve sustainable growth and strengthen their competitiveness.
By analyzing the economic decisions of individuals and businesses, microeconomics helps us understand the fundamental elements of economic activity and their effects. Various factors, including individuals' consumption decisions, businesses' production strategies, the laws of demand and supply, and market structure and competition, interact to shape markets.
This understanding of microeconomics plays an important role in policymaking, business strategy, and improving economic efficiency. Going forward, microeconomics will continue to make even more detailed and practical economic analysis and forecasting possible.